How Collateral Borrowing Works for Fast Cash
Collateral borrowing allows you to obtain immediate funds by pledging a valuable possession as security rather than relying solely on your credit history. When you take out a collateral loan, the lender holds either physical possession of the asset or a legal claim against its ownership until the debt is settled. Because the loan is backed by tangible property, lenders typically evaluate the secondary market value of the item instead of running extensive credit bureau inquiries.
Traditional pawn transactions involve leaving a portable personal item, such as a watch or musical instrument, inside a secure shop vault for thirty to ninety days. If you repay the principal balance alongside state-mandated interest and storage fees within the agreed term, the pawnshop hands your item back immediately. If you fail to repay, the lender simply liquidates the property to satisfy the outstanding debt without reporting a default to credit agencies.
A car collateral loan operates under the same fundamental premise of secured debt, but it carries far higher financial stakes. Instead of handing over a small item across a counter, you pledge the clear title of your daily transportation in exchange for a short-term cash advance. Understanding the distinctions between these two types of secured lending helps you determine whether risking a critical asset makes financial sense for your circumstances.
The Mechanics of an Auto Title Loan
When you use a car title for a loan, you permit a specialty lender or licensed pawn broker to place a temporary legal lien on your vehicle title. In exchange, the lender issues a cash loan calculated as a percentage of the vehicle's wholesale liquidation value, typically ranging from twenty-five to fifty percent. You surrender the paper title certificate to the lender while continuing to drive your car as usual during the duration of the repayment term.
To execute this transaction, most automobile title loans require you to own the vehicle outright, meaning the original purchase financing must be fully satisfied with no existing liens on the title. The lender physically inspects the vehicle to record mileage, assess mechanical condition, document body damage, and verify the vehicle identification number. Once both parties sign the security agreement, the lender holds the title document until the balance is cleared.
Repayment windows for auto title loans are notoriously brief, typically structured as thirty-day balloon payments or structured across three to twelve monthly installments. If you pay off the complete loan principal plus accrued interest by the maturity date, the lender releases the lien at the state motor vehicle agency and returns your clean title certificate. Failing to settle the balance triggers strict contractual remedies outlined in the original agreement.
Title Lending Versus Traditional Pawn Shop Loans
While both structures fall under the umbrella of loans using collateral, their day-to-day consequences for the borrower differ dramatically. When you pawn household goods at local shops, you lose physical access to the asset immediately, but you risk nothing beyond that specific item. If your budget collapses and you forfeit the item, your daily routine, ability to commute to your job, and personal mobility remain completely unaffected.
In contrast, vehicle title loans allow you to maintain possession of the car while you repay the money, which makes them appealing to people who need cash but must drive to work. However, this convenience introduces severe operational vulnerability into your household budget. Defaulting on a traditional pawn ticket simply closes the transaction, whereas defaulting on a car collateral loan can result in the sudden repossession of the vehicle you depend on every morning.
Borrowers often turn to specialized pawn shops offering car title loans because the loan limits are substantially higher than what standard personal merchandise commands. An everyday laptop or power tool set might fetch fifty to two hundred dollars, whereas a dependable pickup truck or sedan can unlock several thousand dollars in collateral funding within a single afternoon.
Documentation and Equity Needed to Qualify
Qualifying for a loan using a car as collateral requires specific documentation that establishes clear ownership and your capacity to handle the agreement. The primary requirement is a lien-free title in your legal name, showing no secondary financial institutions or joint owners who have not signed the paperwork. Some lenders consider secondary financing arrangements, but these auto loan title loan variations are rare and carry significantly tighter terms.
Beyond the title certificate, lenders typically require a valid government-issued photo identification, proof of residential address via utility bills, and evidence of recurring income through pay stubs or bank statements. While a formal credit score is rarely the determining factor, the lender must verify that you have reliable incoming cash flow to cover the monthly financing charges and avoid an immediate repossession scenario.
The lender also inspects the vehicle directly or requests detailed digital photographs showing the exterior panels, tire tread, odometer reading, and interior condition. In most states, lenders cross-reference the vehicle identification number against national title databases to verify that the automobile does not carry a salvage, flood, or rebuilt brand, which drastically reduces collateral appeal and maximum allowable loan amounts.
Understanding Interest Rates and the True Cost of Borrowing
The financial charges associated with vehicle title loans and short-term collateral advances are among the highest in the consumer lending market. Monthly interest rates typically range from fifteen to twenty-five percent in states where title lending is lightly regulated. When translated into an annualized percentage rate (APR), this equates to roughly two hundred to three hundred percent, making long-term carrying costs extraordinarily burdensome.
Consider a scenario where you borrow one thousand dollars at a monthly rate of twenty percent. At the end of thirty days, you owe one thousand two hundred dollars to satisfy the agreement. If you cannot produce the entire sum, the lender may permit you to roll the loan over by paying only the two hundred dollars in finance fees. If you roll over the debt for six consecutive months, you pay twelve hundred dollars in interest alone while still owing the initial one thousand dollars.
Depending on the jurisdiction, local statutory caps govern how much interest a lender can legally assess on secured personal transactions. For example, regulated pawn shops in Texas operate under distinct fee schedules compared to lenders in other states, where interest rates and maximum administrative fees are closely monitored by consumer credit commissioners to prevent predatory roll-over cycles.
The Reality of Default and Vehicle Repossession
Defaulting on an automobile collateral agreement triggers the lender's contractual right to seize the property without obtaining an advance court order. In most states, once a scheduled payment is missed and any grace period expires, the title lender can dispatch a commercial repossession agency to recover the vehicle from your driveway, workplace parking lot, or street curb at any hour.
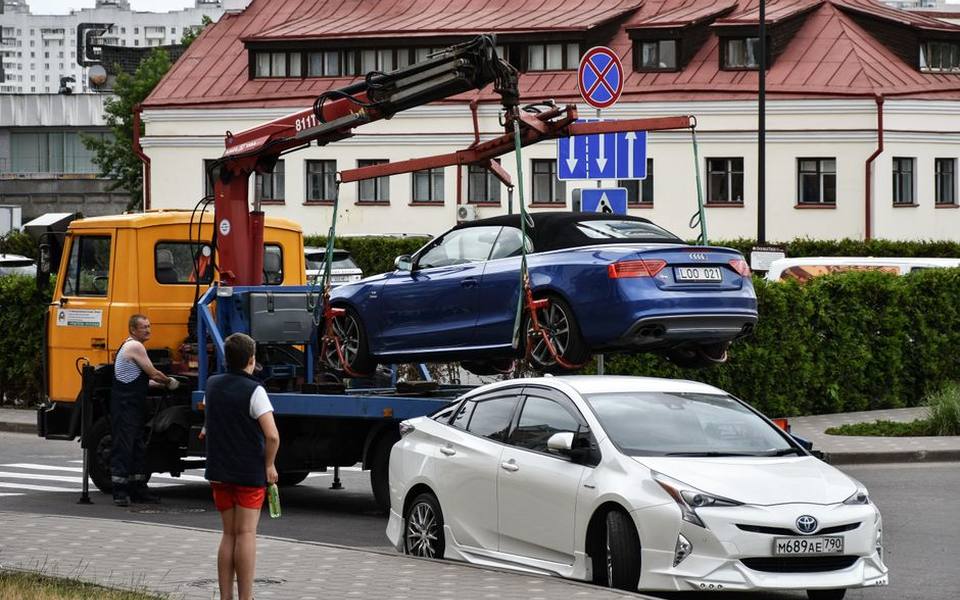
After repossession occurs, the lender provides written notice detailing the exact amount required to redeem the vehicle, which includes the outstanding principal, unpaid interest, late penalties, and third-party towing and daily lot storage fees. If you cannot produce the full redemption balance within the statutory window, which typically spans ten to twenty-one days, the lender sends the car to a wholesale dealer auction.
Auction proceeds are applied directly toward your unpaid debt and associated recovery expenses. Depending on state statutes, if the car sells for more than the total balance owed, the lender must remit the surplus funds back to you. However, if the auction sale price falls short of the balance, certain jurisdictions permit the lender to pursue you in court for the remaining deficiency balance.
Evaluating Online Pawn Shops and Remote Borrowing Options
The rise of digital platforms has introduced the online pawn shop model, which lets consumers borrow against high-value items without visiting a storefront counter. For vehicle transactions, online title loan providers use digital application portals where you upload photographs of your vehicle, images of your clean title, and digital verification of your monthly income to secure a preliminary loan estimate within minutes.
While digital convenience speeds up underwriting, remote title agreements still require vehicle verification and legal lien registration before cash is disbursed. Some virtual lenders send a local mobile notary or inspection agent to review your car in person, while others partner with regional brick-and-mortar pawn establishments where you drop off your title in exchange for direct deposit or immediate cash payout.
When exploring digital collateral borrowing, exercising caution regarding state licensing is critical. Legitimate collateral lenders must hold active operational licenses in the specific state where the borrower resides. Working through unvetted offshore platforms or unregulated online lenders often exposes borrowers to illegal interest schedules, hidden processing charges, and non-existent customer service if dispute issues arise regarding payments.
Pawning Valuable Household Assets as a Safer Alternative
Before putting your primary mode of transportation at risk, explore whether parting temporarily with smaller personal valuables can generate the required funds. Established pawn shops for jewelry regularly issue collateral loans against diamond rings, luxury watches, and designer pieces without placing your personal mobility in jeopardy or demanding access to your vehicle's ownership paperwork.
Similarly, dealing with verified gold and precious metal buyers allows you to liquidate obsolete jewelry, scrap dental gold, bullion, or rare coins for direct settlement. Because gold maintains an easily verifiable spot market price, pawn counters and precious metal specialists can provide quick loan appraisals without requiring proof of employment, personal references, or formal bank statements.
Opting to borrow against non-essential merchandise eliminates the single greatest danger of title lending: losing your ability to travel to work. If an emergency expenses crisis deepens and you forfeit a gold chain or an extra camera kit, you absorb a property loss, but your household infrastructure and employment income remain completely protected from repossession agents.
How to Read and Negotiate Your Collateral Loan Agreement
Signing any collateral loan contract demands rigorous inspection of the fine print before taking possession of the cash. Federal truth-in-lending rules mandate that licensed lenders supply a written disclosure sheet highlighting the total amount financed, the exact finance charges in dollars, the annualized interest rate, and the precise payment schedule, including the exact balloon payment maturity date.
Pay strict attention to ancillary fees that lenders frequently bundle into title loan transactions. These add-ons may include title transfer processing fees, document preparation surcharges, mandatory vehicle GPS tracking installation fees, and roadside assistance subscriptions. These charges inflate your initial loan balance and reduce the net cash in your pocket while compounding your monthly interest burden.
Verify whether the agreement includes an early prepayment penalty. High-interest collateral debt should ideally be eliminated as rapidly as possible, so your contract must explicitly permit partial payments or early principal payoffs without assessing early termination penalties. If the counter agent refuses to explain any ambiguous clause clearly, walk away and locate a different licensed lending establishment.
A Sensible Checklist Before Surrendering Your Vehicle Title
Before handing over your vehicle title to secure immediate cash, perform an honest audit of your finances to ensure you have a viable exit path. Confirm that your monthly income provides enough surplus after food, rent, and utility expenses to extinguish the loan balance inside thirty to sixty days, rather than leaving you trapped paying continuous rollover fees.
Make duplicate copies of your title certificate, your vehicle registration, and your driver's license before signing the original title over to the lending establishment. Ask the loan officer to outline the precise protocol for recovering your clean title once the final installment clears, including whether they handle lien release paperwork at the state motor vehicle agency directly or mail the released title to your home.
Finally, determine your backup transportation plan in the worst-case scenario. If unexpected financial complications prevent you from satisfying the loan and your car is repossessed, you must know how you will commute to your workplace to earn a living. If losing the vehicle means losing your primary livelihood, borrowing against your car title is far too dangerous a risk to assume.
Published 2026-09-23 · reviewed with each rebuild, last October 2026.
Find pawn shops & check cashing stores near you
The directory lists 29,004 pawn shops & check cashing stores by state and city — pick your state or use the “Near me” button in the header.
More guides
-
 Money
How to Buy Money Orders and Send Wire Transfers
-
 Money
How to Buy and Sell Silver Bullion, Coins, and Sterling
-
 Service
Watch Battery Replacement and Sizing Guide: Costs, Links, and Services
-
 Money
Where and How to Sell a Used iPhone for Cash Today
-
 Service
Ring Resizing Costs, Metal Limits, and Local Repair Options
-
 Buying
Where to Buy and Sell Pokemon, Sports, and Trading Cards
-
 Money
How to Sell Gold Jewelry, Scrap Gold, and Diamonds
-
 Money
How to Buy, Value, and Sell Used Rolex Watches
-
 Money
Complete Guide to Check Cashing Services and Fast Cash Advances
-
 Money
How to Use In-Store Money Transfer and Foreign Currency Exchange Services
-
 Buying
How to Buy Used TVs, Modern Consoles, and Retro Games at Pawn Shops
-
 Service
Guide to Custom Jewelry Design, Engraving Services, and Gold Grillz
-
 Buying
 Certified Refurbished MacBooks and Laptops: Pawn and Resale Guide
-
 Money
Authentic Designer Handbags: How to Value, Authenticate, and Pawn Luxury Purses
-
 Money
Gold and Silver Bullion Trading: Cash for Precious Metals Guide